Professional indemnity (PI) insurance protects you if a client says your professional advice, design or service was wrong and cost them money. It pays for the legal defence of the claim and, where you’re found liable, the compensation you owe, up to the limit on your policy.
If you sell expertise rather than physical products, this is the cover that responds when that expertise is questioned.
How professional indemnity insurance works
A client relies on your work, something goes wrong, and they suffer a financial loss. They then claim against you, alleging negligence, an error or an omission. You don’t need to have actually made a mistake for a claim to be costly. Defending a claim you eventually win still means legal fees, expert reports and weeks of your time.
PI insurance steps in at that point. Your insurer typically:
- Appoints and pays for legal representation
- Investigates the claim with you
- Negotiates or settles where appropriate
- Pays compensation if you’re found legally liable, up to your limit of indemnity
Bi-me’s professional indemnity cover is underwritten by iToo, a specialist insurer.
What does PI insurance protect against?
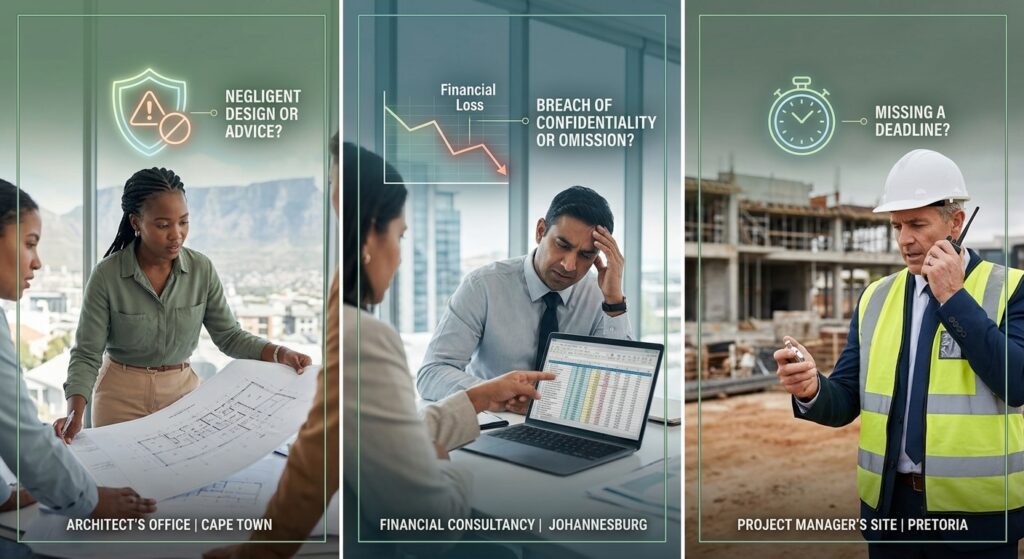
PI cover responds to financial loss suffered by a client or third party because of your professional work. Typical triggers include:
- Negligent advice or a design error
- A mistake or omission in a report, calculation or specification
- Missing a deadline that causes your client a loss
- Breach of confidentiality
- Unintentional defamation or infringement of intellectual property (depending on the wording)
We cover this properly in What Does Professional Indemnity Insurance Cover in South Africa? The exact protection always depends on your policy wording and schedule.
Who needs professional indemnity insurance?
Anyone whose income depends on advice, expertise or professional judgement. That includes:
- Built environment: architects, engineers, quantity surveyors, project managers
- Advisory: business, HR, IT and management consultants
- Financial and administrative: accountants, bookkeepers, assessors, loss adjusters
- Property: estate agents and property valuers
- Health and wellness: some practitioners, depending on whether medical malpractice cover is more appropriate (see below)
Freelancers and sole proprietors need it too. As a sole trader, your personal assets are on the line, not a company’s.
Three terms that decide whether you’re covered
1. Claims-made basis
PI insurance is usually written on a claims-made basis. The policy responds to claims that are made against you and reported to the insurer during the policy period. The work may have been done years earlier, but if the claim first arrives after your policy has lapsed, it may not be covered.
Practical takeaway: don’t let PI cover lapse, even after you stop trading, without asking about run-off cover.
2. Retroactive date
The retroactive date is the earliest date from which past work is covered. Work you did before that date is generally excluded. When you switch insurers, preserving your original retroactive date is one of the most important things you can do. We explain this in What Is a Retroactive Date in Professional Indemnity Insurance?
3. Limit of indemnity and excess
The limit of indemnity is the most the insurer will pay for a claim (and often across the policy period). The excess is the amount you pay first. Choosing a limit that’s too low is the most common way people end up underinsured. See How Much Professional Indemnity Insurance Do I Need?
An illustrative example
This is a hypothetical scenario, not a real claim.
A consultant produces a feasibility study for a client planning to open a new branch. The study overlooks a zoning restriction. The client signs a lease, spends money on a fit-out, then learns the site can’t be used as planned. They claim against the consultant for their wasted costs.
With PI cover, the insurer would handle the defence and, if the consultant were found liable, pay the settlement within the policy limit, less the excess. Without it, the consultant would fund both from their own pocket.
What PI insurance does not cover
PI is not a catch-all. It generally does not cover bodily injury or property damage (that’s public liability), fraud or dishonesty by you, or claims you already knew about before the policy started. Read What Does Professional Indemnity Insurance Not Cover? before you buy.
It is also different from public liability insurance. Many professionals need both.
Frequently asked questions
Is professional indemnity insurance the same as medical malpractice insurance?
They’re closely related. Both cover liability arising from professional services, but malpractice cover is designed for health practitioners and their specific risks. Which is right for you depends on your profession.
Do I need PI insurance if I work for an employer?
Often your employer’s policy covers your work as an employee, but not always, and not for side work. Check with your employer, and consider your own cover for any freelance activity.
Is PI insurance compulsory in South Africa?
Not for everyone, but some regulators, clients and tenders require it. See Is Professional Indemnity Insurance Compulsory in South Africa?
Can I get cover for past work?
That depends on the retroactive date on your policy. Ask your broker to confirm it in writing.
Get covered with Bi-me
Compare options, choose a limit that fits your work, and get a quote online.
Get a professional indemnity quote →
Or read more about professional indemnity insurance from Bi-me.