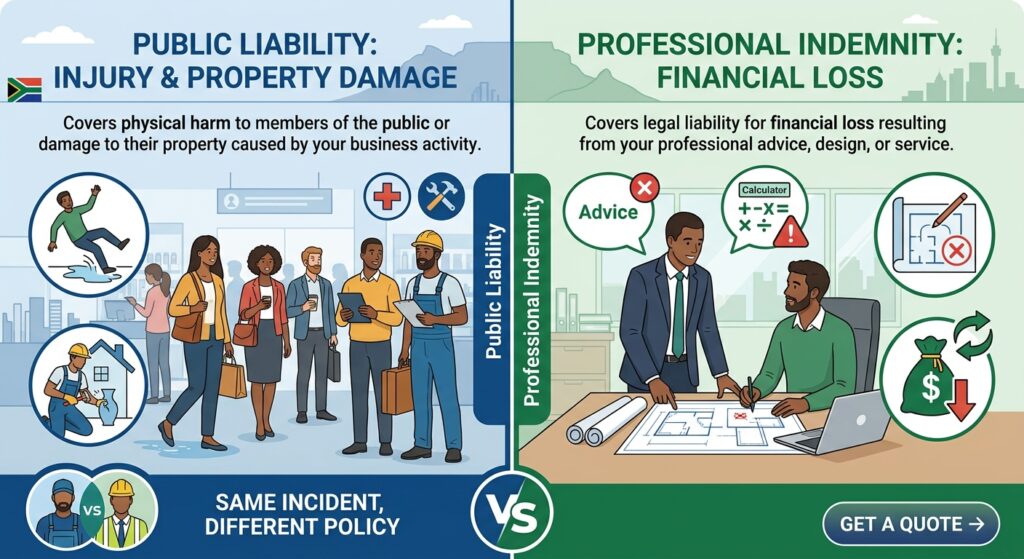
Public liability vs professional indemnity comes down to what went wrong. Public liability responds when your business causes injury or damage to someone’s property. Professional indemnity responds when your advice, design or service causes a client a financial loss. Many businesses need both.
Public liability vs professional indemnity at a glance
| Public liability | Professional indemnity | |
|---|---|---|
| Protects against | Injury to people or damage to their property | Financial loss caused by your advice, design or service |
| Typical claimant | Customer, visitor, supplier, member of the public | Client |
| Typical trigger | An accident connected to your business activity | An error, omission or negligent advice |
| Example loss | Medical costs, damaged property | Rework costs, lost profit, wasted spend |
| Usually excludes | Losses from professional advice or services | Bodily injury and property damage |
What public liability insurance covers
Public liability protects you when your business activity accidentally injures someone or damages their property. That includes claims from customers, suppliers and members of the public. Typical examples:
- A customer slips on a wet floor at your premises
- A contractor’s work damages a client’s property
- A fire that starts on your premises spreads to a neighbour’s
What professional indemnity insurance covers
Professional indemnity protects you when a client says your professional error, omission or negligent advice cost them money, and it covers the legal costs of defending the claim. Typical examples:
- A miscalculated estimate that leads a client to overspend
- A specification that doesn’t match the brief
- Advice that proves wrong
See What Does Professional Indemnity Insurance Cover? for the detail.
Same incident, different policy
| Scenario | Likely policy |
|---|---|
| A plumber’s leak floods a client’s home | Public liability (property damage) |
| A visitor trips over cables in your office | Public liability (injury) |
| An engineer’s calculation error forces rework | Professional indemnity (financial loss) |
| A consultant’s advice leads to a failed launch | Professional indemnity (financial loss) |
| A design flaw leads to a collapse that injures a worker | Grey zone. See below |
The grey zone: injury caused by professional error
Injury or damage that results from a professional mistake can fall between the two policies. Public liability wordings usually exclude claims arising from professional services, and PI wordings usually exclude bodily injury. Before you assume you’re covered, ask your broker how each policy would respond to an injury caused by your professional work.
Which do you need?
| If you are… | Public liability | Professional indemnity |
|---|---|---|
| A tradesperson or sole trader | Essential | If you design or specify, not just install |
| A freelancer or consultant | If clients visit you or you work on their premises | Essential |
| An architect, engineer or quantity surveyor | If you visit sites or receive visitors | Essential |
| A design-and-build contractor | Essential | Essential |
| A property practitioner | If you show properties or host visitors | Essential |
| A shop, café or venue | Essential | If you also give advice or design services |
Public liability is not a legal requirement for most businesses, but clients, landlords, venues and tenders often ask for it. For PI, see Is Professional Indemnity Insurance Compulsory?
Do you need both?
Ask two questions:
- Could my business physically injure someone or damage their property? If yes, you need public liability.
- Could my advice, design or service cost a client money? If yes, you need professional indemnity.
If you answered yes to both, you need both. That’s true for most professionals who work on client premises or sites.
Questions to ask a broker
- Do these policies have separate limits and wordings, or are they bundled?
- How would each respond to injury caused by my professional work?
- Do I need cover for work done at a client’s premises?
- What’s my excess on each policy?
Frequently asked questions
Does public liability cover professional advice?
Generally not. Most wordings exclude claims arising from professional services. That’s what PI is for.
Can I get both in one policy?
Some insurers package both, but each cover keeps its own limit, wording and exclusions. Check each part separately.
If I’m a sole trader, which comes first?
If you work with your hands, public liability usually comes first. If you sell expertise, PI does. If you do both, you need both.
Is one cheaper than the other?
It varies by profession, work type and limit. Get quotes on both and compare.
Cover both risks
Tell us what you do and where you do it, and we’ll help you find the right combination.
Get a professional indemnity quote → | Get a public liability quote →