Is professional indemnity insurance compulsory in South Africa? For most professionals, no. For some, yes, and for many more it’s effectively required by clients, tenders and professional bodies. Whether you must carry it depends on your profession, your regulator and the contracts you sign. So the useful question isn’t “is it the law?” but “who is requiring it of me?”
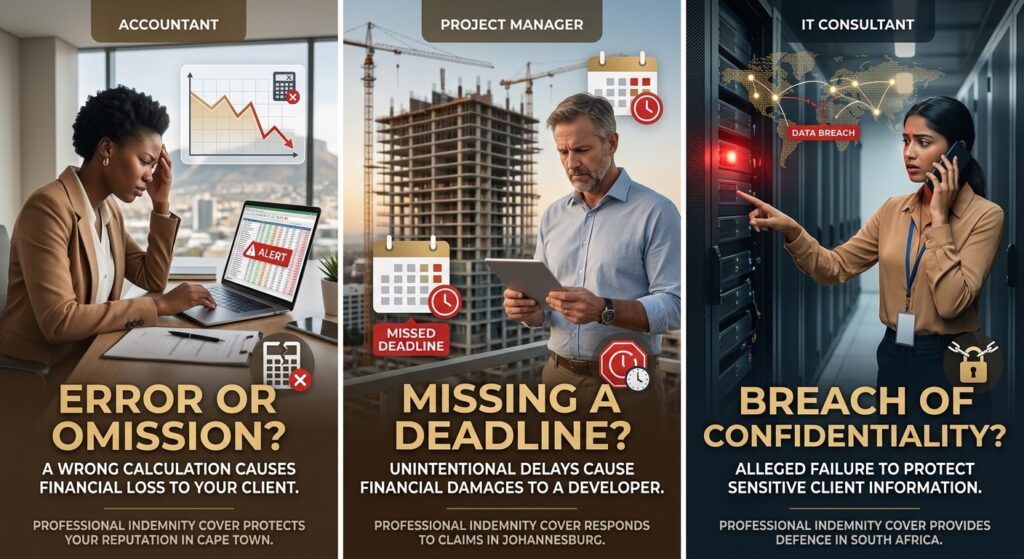
The short answer: three ways PI becomes compulsory
- By law or licence condition. A statute or regulator requires it for certain professions.
- By professional body rules. Your body requires members in public practice to hold it.
- By contract. A client, employer or tender requires proof of cover before you start.
Most professionals meet the third route, not the first.
Where professional indemnity insurance is compulsory by law or licence
Financial services providers (FAIS)
Financial services providers licensed under the Financial Advisory and Intermediary Services Act (FAIS) are generally required to hold PI cover. The FSCA sets the requirements, and the minimum amount depends on your licence category. SAIPA’s guidance on PI limits notes that FSPs face a legal minimum of R1 million. Higher minimums apply to some categories, so confirm the current figure for yours with the FSCA.
Attorneys and advocates
Legal practitioners with a Fidelity Fund Certificate are covered by a primary layer of PI through the Legal Practitioners Indemnity Insurance Fund (LPIIF). That layer is a foundation, not a ceiling. It applies across the whole practice, so many firms buy top-up cover above it.
Property practitioners
A Fidelity Fund Certificate (FFC) from the PPRA is compulsory to practise as a property practitioner. An FFC is not professional indemnity insurance. The fund exists mainly to compensate the public when trust money is stolen. The Property Practitioners Act also lets the Minister prescribe indemnity insurance, so check with the PPRA for what currently applies to you.
Accountants, auditors and tax practitioners
Some professional bodies require members in public practice to carry PI, and certain engagements carry their own requirements. The obligation sits in your body’s rules rather than in general law, so check the current rules of the body you’re registered with.
Health practitioners
Health professionals usually need malpractice cover, a closely related product. See medical malpractice insurance and check your council’s current rules.
Architects, engineers and quantity surveyors
Registration with SACAP, ECSA or SACQSP is required to practise these professions. Whether PI is a condition of registration can change, so check with your council. In practice, many clients and public tenders require proof of cover regardless.
Where professional indemnity insurance is compulsory by contract
This is where most professionals actually get caught. PI is often a condition of:
- Client contracts and master services agreements
- Public-sector and corporate tenders. See our tender documents checklist.
- Subcontracting arrangements where the main contractor passes its own requirements down
Read the insurance clause carefully. It may set:
- A minimum limit of indemnity
- How long cover must continue after the project ends
- Whether the client must be noted on the policy
You prove cover with a certificate. Bi-me policyholders can get theirs from the certificates of insurance page.
What happens if you skip cover you’re required to have?
- You can lose a tender or contract if you can’t produce proof in time.
- Where a law or licence requires cover, you may face regulatory consequences.
- If a claim arrives, you carry the full cost of defence and compensation yourself.
If it isn’t compulsory, why do professionals still buy it?
- Sole proprietors have no separation between personal and business assets.
- Defending a claim costs money even if you win it.
- Claims can arrive years later. PI is usually claims-made, so cover has to be in place when the claim is made.
- Clients increasingly ask for proof before they’ll sign.
See What Does Professional Indemnity Insurance Cover? for what you’d be buying.
How to find out whether you must carry PI
- Check your regulator or professional body’s current rules.
- Read the insurance clauses in your existing contracts.
- Check tender documents for minimum cover requirements.
- Ask your employer whether your work is covered by their policy, and whether that includes side work.
- Ask a broker. It takes a few minutes and costs nothing.
An illustrative example
This is a hypothetical scenario, not a real claim.
A freelance consultant finds a tender that suits her perfectly. Page 14 requires proof of professional indemnity cover of a stated minimum, and the closing date is in three days. She has no cover, and the tender goes to a competitor. Nothing went wrong on any project. The requirement simply arrived before she did.
Frequently asked questions
Is professional indemnity insurance compulsory for sole proprietors?
There’s no general law requiring it, but the same profession-specific and contractual requirements apply to you as to anyone else.
Is there a legal minimum limit?
Only where a regulator or body sets one, as with FSPs. Otherwise the minimum comes from your contracts. See How Much Professional Indemnity Insurance Do I Need?
Do I need PI if I already have public liability?
Yes. Public liability covers injury and property damage. PI covers financial loss from advice or services. See Public Liability vs Professional Indemnity.
Am I covered by my employer’s policy?
Often for your work as an employee, but not always, and not for side work. Ask in writing.
This is general information, not legal advice. Confirm requirements with your regulator or professional body.
Get the proof you need
Tell us your profession and what your contracts require, and we’ll help you get cover that meets it.