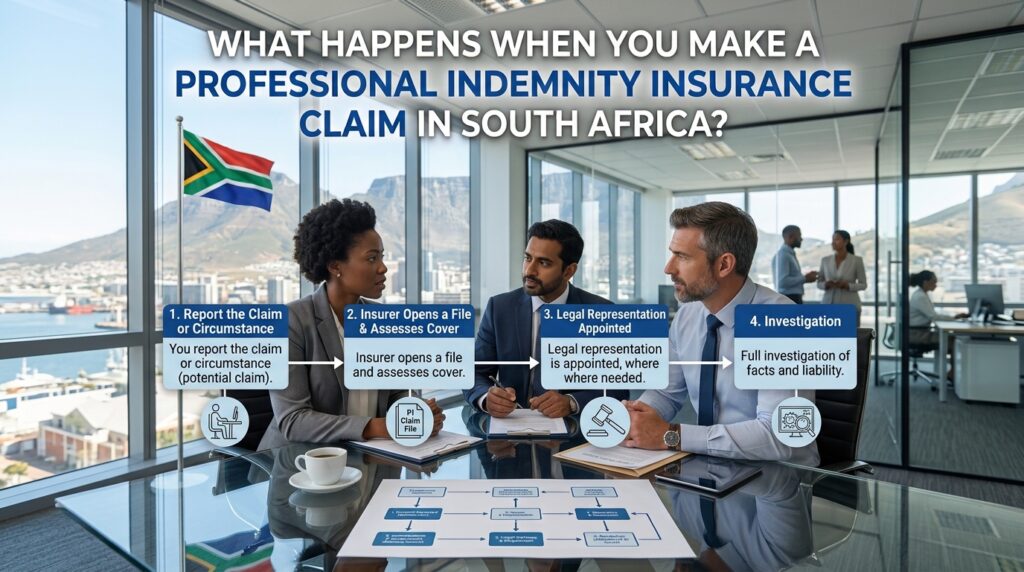
A professional indemnity insurance claim starts the moment you become aware of a problem, not when a letter of demand arrives. From there, your insurer investigates, appoints legal representation if needed, and either defends the claim, negotiates a settlement, or pays out, up to your limit of indemnity. Here’s what that process actually looks like.
The most important step happens before there’s a “claim”
Most PI policies require you to notify your insurer of circumstances that may give rise to a claim, not just formal claims. That includes:
- A client complaint about your work
- Discovering your own error, even if the client hasn’t noticed yet
- A dispute that hasn’t turned into legal action yet
- Any situation where you think, “this could become a problem”
Report early. South African case law and industry guidance are consistent on this: late notification can lead an insurer to reject a claim entirely, even if the underlying claim would otherwise have been covered. Reporting a circumstance is not an admission that you did anything wrong. It simply puts your insurer on notice so they can help you manage it.
This section is general guidance, not legal advice. If you’re unsure whether something needs to be reported, ask your broker or insurer rather than waiting.
Step-by-step: what happens after you notify your insurer
1. You report the claim or circumstance
Notify your insurer or broker as soon as you’re aware of it. Provide what you have: correspondence, the contract, your notes, and a plain account of what happened. You don’t need a complete legal analysis, just the facts as you understand them.
2. The insurer opens a file and assesses cover
The insurer checks whether the policy was active at the relevant time, whether the work falls after your retroactive date, and whether the claim fits within your cover. This is also when any exclusions get tested. See What Does Professional Indemnity Insurance Not Cover?
3. Legal representation is appointed, where needed
For anything beyond a simple query, the insurer typically appoints attorneys to represent you. This usually happens while the insurer is still deciding on indemnity, so you’re not left unrepresented during that period.
4. Investigation
Your insurer and their legal team investigate the facts: reviewing documents, correspondence, and your account of events, and sometimes involving expert witnesses in technical fields such as engineering or construction.
5. Defence, negotiation, or settlement
Depending on what the investigation finds, the claim is either:
- Defended, if there’s a good basis to dispute liability
- Settled, if a negotiated resolution is more sensible than litigation
- Paid, if liability is clear and within your cover
6. Resolution
The insurer pays compensation up to your limit of indemnity, less your excess, where liability is established or a settlement is reached. Defence costs are handled according to your policy wording, either inside or outside that limit.
How long does it take?
There’s no fixed timeline. A straightforward matter might resolve in a few months. A disputed claim, especially one that goes to formal legal proceedings, can run for a year or more. Complex professional negligence claims are rarely quick, which is part of why the legal defence cover matters as much as the compensation cover.
What you should and shouldn’t do
Do:
- Notify your insurer immediately, including for circumstances, not only formal claims
- Keep all documentation: contracts, emails, drawings, reports, correspondence
- Cooperate fully with the investigation
- Ask your insurer or broker if you’re unsure whether something needs reporting
Don’t:
- Admit liability to the client before your insurer has assessed the claim
- Negotiate or correspond about the claim without your insurer’s knowledge
- Assume it will “blow over” and skip notification
- Wait for a formal letter of demand before you report a problem you already know about
An illustrative example
This is a hypothetical scenario, not a real claim.
A quantity surveyor notices, three months after a project closes, that a cost estimate omitted a significant line item. The client hasn’t complained yet. Because the QS reports this to their insurer as a circumstance that may give rise to a claim, the insurer is already aware and engaged when the client does eventually raise it. Had the QS waited for the client’s letter, the delay itself could have put cover at risk.
Frequently asked questions
Do I need to report something even if I don’t think it’s my fault?
Yes, if it’s a genuine circumstance that could give rise to a claim. Let the insurer assess liability. That’s their job, not yours to pre-judge.
Will making a claim affect my premium?
It can, depending on the claim and your insurer’s underwriting approach. This is a conversation to have with your broker, but it should never stop you from reporting something you’re required to report.
What if the claim is rejected?
Ask why. It may relate to an exclusion, a disclosure issue, or late notification. Your broker can help you understand the decision and whether it can be challenged.
Can I claim if I’m no longer trading?
Only if you have cover in place when the claim is made, which is why run-off cover matters when you stop practising. See The Risks of Cancelling Your Professional Indemnity Insurance
If something’s gone wrong, don’t wait
Report it to us as soon as you’re aware of it. Early notification protects your cover.